
If you run a business today, there is a strong chance you already rely on at least one Software as a Service (SaaS) application — whether that is a CRM platform, a productivity suite, or a project management tool. Even free consumer services such as email, social media, and video platforms follow the SaaS delivery model; they are simply monetised through advertising rather than subscription fees.
Beyond consumer apps, SaaS is fundamentally restructuring how enterprise software is built, sold, and maintained. The traditional model — buy a perpetual licence, install on-premises, patch manually — is giving way to on-demand, subscription-based cloud delivery. Understanding why this shift is happening, and what it means for software delivery practices, is increasingly important for engineering and DevOps teams.
From Perpetual Licences to Pay-As-You-Go
The traditional software licensing model required customers to pay a large upfront cost, manage their own infrastructure, and absorb the risk of version upgrades. SaaS inverts this model entirely:
- Lower barrier to entry: Customers pay a recurring subscription rather than a large capital expenditure.
- Continuous delivery: Vendors push updates to all customers simultaneously, eliminating version fragmentation.
- Elastic scaling: Capacity scales with usage, removing the need for customers to over-provision hardware.
- Predictable revenue for vendors: Subscription models produce recurring, forecastable revenue streams that the market tends to value more highly than one-time licence sales.
This shift changes the incentives for software vendors. Under a perpetual model, the sale ends at the point of purchase. Under SaaS, the vendor must continuously earn renewal by delivering ongoing value — which directly encourages faster iteration, better reliability engineering, and tighter feedback loops between users and development teams.
Enterprise SaaS Market Growth
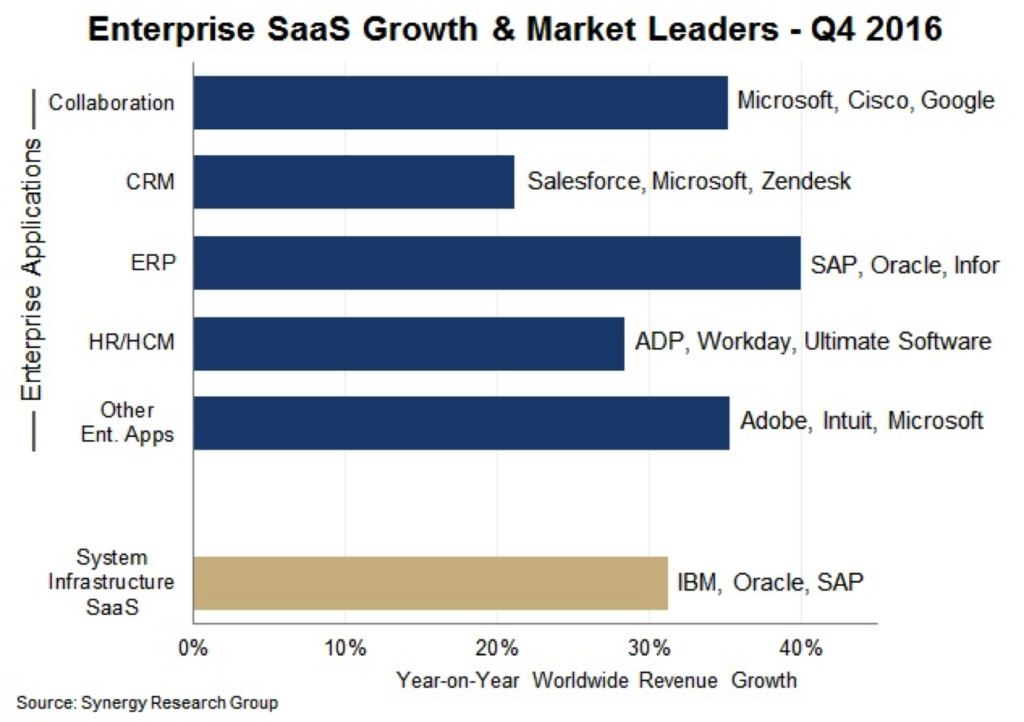
The enterprise SaaS market was already growing sharply by the mid-2010s. According to data from Synergy Research Group cited in a 2017 report, the enterprise SaaS market grew approximately 32% year-over-year to reach around $13 billion in quarterly revenues. IDC, quoted in the same period, projected the broader cloud software market — which stood at roughly $48.8 billion in 2014 — would surpass $112 billion by 2019, growing at a compound annual rate of around 18%.
These figures are now several years old and the market has grown substantially since, but they illustrate the trajectory: SaaS was already outpacing traditional software delivery growth by a wide margin, and that gap has continued to widen.
Key Players and Market Dynamics
Microsoft
Microsoft’s transition to SaaS is one of the most significant corporate pivots in software industry history. The company moved its flagship Office productivity suite to a subscription model (Office 365, now Microsoft 365), and extended this approach to enterprise resource planning with Dynamics 365. By the mid-2010s, Synergy Research Group identified Microsoft as the leading enterprise SaaS vendor by revenue, primarily through collaboration and productivity software.
A notable aspect of Microsoft’s strategy is deliberate internal cannibalisation: Office 365 directly competes with the company’s own volume-licensed Office commercial products. Despite this, the productivity and business processes segment continued to grow, demonstrating that subscription conversion can more than offset declines in legacy licence revenue when executed at scale.
Salesforce
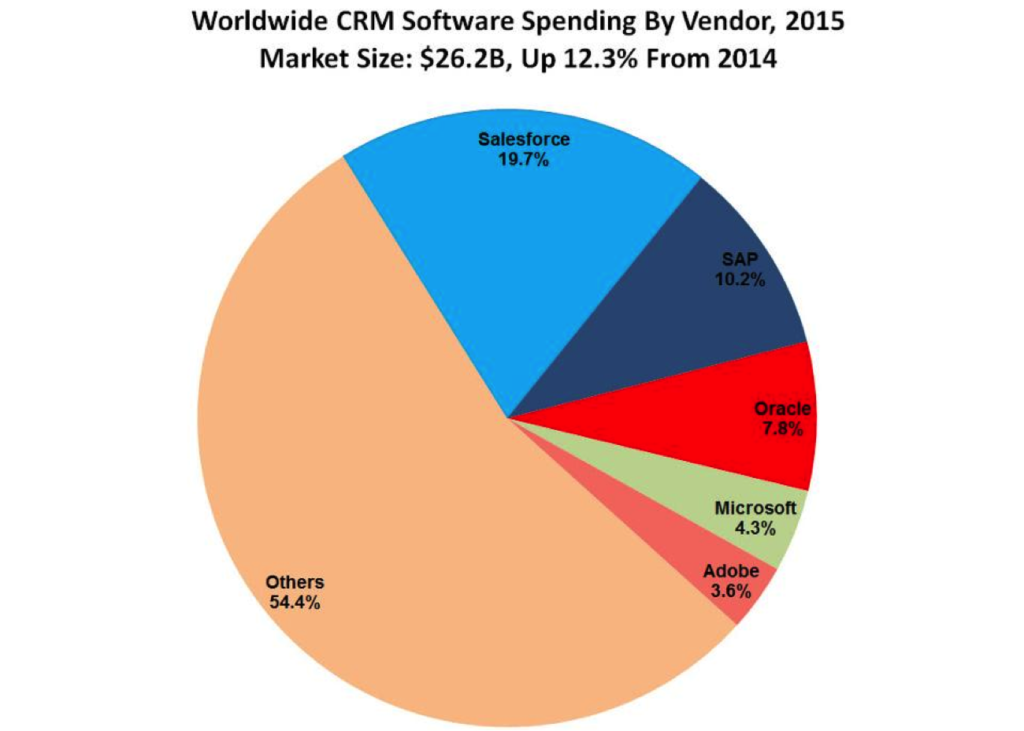
Salesforce built its entire business on the SaaS model from the outset, targeting customer relationship management (CRM) software — a category that had previously been dominated by on-premises products from SAP and Oracle. By moving CRM to the cloud and offering per-user monthly pricing, Salesforce lowered adoption friction significantly and grew to hold approximately 20% of the global CRM market by 2015, reportedly exceeding the combined share of SAP and Oracle at the time.
Oracle and the NetSuite Acquisition
Oracle, historically a stronghold of on-premises enterprise software, recognised the competitive threat SaaS posed to its core business. In 2016, the company acquired NetSuite for approximately $9.3 billion — at the time one of the largest cloud software acquisitions on record. NetSuite was a leading cloud ERP vendor, and the acquisition gave Oracle an established SaaS customer base and product portfolio in a segment it had been slow to address organically.
What the SaaS Shift Means for Software Delivery
The move from packaged software to SaaS is not simply a commercial or pricing change — it restructures the entire software delivery lifecycle. For engineering and DevOps teams, the implications are significant:
- Continuous deployment becomes necessary, not optional: SaaS vendors cannot ship annual releases. Customer expectations for new features and rapid bug fixes require mature CI/CD pipelines and automated testing.
- Reliability engineering is a product differentiator: When software is delivered as a service, downtime directly impacts customers and generates churn. SRE practices, SLOs, and incident management become core business functions.
- Multi-tenancy and security by design: Running shared infrastructure for many customers requires architectural patterns — tenant isolation, data encryption at rest and in transit, role-based access control — that are optional in on-premises deployments but mandatory in SaaS.
- Observability at scale: SaaS operators need visibility into system behaviour across all customer tenants simultaneously, driving adoption of centralised logging, distributed tracing, and metrics platforms.
- Feature flagging and progressive rollouts: Unlike packaged software releases, SaaS updates must be rolled out safely to large customer bases, making feature flags and canary deployments standard practice.
The Broader Impact: Democratising Advanced Capabilities
One underappreciated consequence of the SaaS model is that it places enterprise-grade capabilities — analytics, machine learning, natural language processing, and even quantum computing research environments — within reach of organisations that could never have afforded to build or host such systems themselves. Cloud providers now offer these as managed services, accessible via API, billed per use.
This has compressed the competitive gap between large enterprises with significant IT budgets and smaller organisations. A startup can access the same data warehousing, ML inference, or fraud detection infrastructure as a Fortune 500 company, paying only for what it uses.
SaaS Is Expanding the Market, Not Just Shifting It
A common concern when SaaS growth is discussed is whether it simply represents buyers switching payment models rather than genuine market expansion. The evidence suggests it is both. SaaS does cannibalise perpetual licence revenue — Microsoft’s own transition demonstrates this — but it also enables entirely new categories of buyers who were previously priced out of enterprise software.
Per-seat, per-month pricing with no infrastructure commitment means a ten-person company can use the same CRM, project management, or ERP tooling as a ten-thousand-person enterprise, scaled appropriately. This long tail of smaller customers represents net new market volume that traditional packaged software never captured.
Summary
Cloud computing and the SaaS delivery model have permanently altered how software is built, distributed, and maintained. For DevOps engineers and platform teams, this shift is not just a backdrop — it is a direct driver of the practices that define modern software delivery: continuous deployment, reliability engineering, multi-tenant architecture, and observable systems. The vendors that recognised and embraced this shift early, most notably Salesforce and Microsoft, built durable market positions. Those that delayed, such as Oracle and SAP, had to make large acquisitions to catch up.
The trajectory is clear: subscription-based, cloud-delivered software is the dominant model, and the engineering disciplines required to build and operate it at scale are now foundational skills for any modern software team.
Note: Market figures cited in this article originate from research published around 2016–2017 (Synergy Research Group, IDC, Gartner) and reflect the state of the market at that time. Current figures will differ substantially.