This article draws on reporting originally published by Rashi Aditi Ghosh of the Elets News Network (ENN) for bfsi.eletsonline.com, supplemented with editorial context for a DevOps and technology audience.
What Is Industry 4.0?
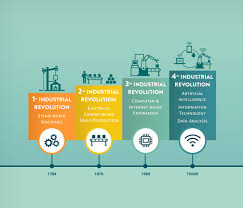
The term Industry 4.0 — or the Fourth Industrial Revolution — describes the current era of digitally driven industrial transformation. To understand why it matters, a brief look at history helps:
- First Industrial Revolution (late 18th century): Water and steam power enabled mechanised production, fundamentally changing manufacturing and labour.
- Second Industrial Revolution: The rise of mass production lines and electrification accelerated output at scale.
- Third Industrial Revolution (20th century): Information technology and early automation began replacing manual processes in factories and offices.
- Fourth Industrial Revolution (present): The convergence of the Internet of Things (IoT), artificial intelligence, robotics, big data, and cloud computing is reshaping entire industries — not just manufacturing, but also finance, healthcare, logistics, and more.
Unlike previous revolutions that were largely driven by physical machinery, Industry 4.0 is fundamentally a data and connectivity revolution. The ability to collect, transmit, store, and act on vast amounts of data in real time is its defining characteristic — and that is precisely where cloud computing plays a central role.
Cloud Computing as the Backbone of Industry 4.0
Cloud computing provides the infrastructure and services that make Industry 4.0 technologies practical at scale. IoT devices generate enormous volumes of sensor data; AI and machine-learning workloads require flexible compute capacity; robotic automation systems need low-latency connectivity and high availability. Cloud platforms address all of these requirements in a way that on-premises infrastructure alone cannot efficiently deliver.
An Oracle report titled Cloud: Opening Up the Road to Industry 4.0 surveyed 1,200 technology decision-makers across EMEA in mid-size and large companies. According to the report, 60 percent of respondents said an integrated cloud approach would unlock the potential of disruptive technologies such as robotics and artificial intelligence. The key insight is that compute services tightly integrated with a cloud platform — rather than isolated cloud storage or SaaS tools — are what enable genuinely innovative and disruptive applications in an Industry 4.0 context.
Why the BFSI Sector Is a Leading Cloud Adopter
The Banking, Financial Services, and Insurance (BFSI) sector has been at the forefront of cloud adoption — and for good reason. Financial institutions process enormous transaction volumes, operate under strict regulatory requirements, and face relentless pressure to reduce costs and improve customer experience. Cloud computing addresses all three simultaneously.
Research cited from Harvard Business Review Analytic Services indicates that 74 percent of businesses believe cloud computing has given them a competitive advantage. In the financial services context, this advantage manifests as faster time-to-market for digital products, better fraud detection through real-time analytics, and the ability to scale payment infrastructure during peak demand without over-provisioning hardware.
Diwakar Nigam, Managing Director of Newgen Software, has highlighted that the banking sector’s cloud adoption is driven by four core advantages: scalability, lower capital costs, ease of operations, and resilience. Newgen’s own Cloud/SaaS business reportedly achieved a five-year CAGR of 127 percent at the time of reporting — a figure that reflects broad industry demand rather than being unique to one vendor.
T V Ramanmurthy, General Manager of IT at Bank of Maharashtra, offered a candid perspective on adoption pace: when BHIM and the Unified Payments Interface (UPI) were implemented by the National Payments Corporation of India (NPCI) in 2017, it reportedly took six months before the institution fully recognised how critical cloud infrastructure was to those payment systems. That delay illustrates a common pattern — cloud’s value in financial services is often understood retrospectively, after a scaling event exposes the limits of on-premises systems.
Cloud Adoption Trends in India’s Financial Sector
India represents a particularly important market for cloud-driven Industry 4.0 transformation. NASSCOM data cited in the original reporting projects the Indian cloud market to reach $7.1 billion by 2022. A separate study by enterprise cloud firm Nutanix suggested India was on track to lead the world in hybrid cloud adoption, with hybrid cloud workloads expected to more than triple — from 13 percent in 2018 to 43 percent within 24 months of that report.
IDC projections referenced in the source material suggest that while traditional software would continue to grow (at approximately 11 percent), cloud infrastructure and cloud-based applications were forecast to grow significantly faster — underscoring the structural shift in how enterprise IT budgets are allocated.
“Each and every financial institution in India has its own perception pertaining to leveraging cloud technology in their institution completely. In reference to the current level of digitisation in the country, it is evident to make use of tech-driven initiatives and cloud is definitely going to play a major role in the transformation.”
— Zulkernain Kanjariwala, Head of IT, Doha Bank
Key Benefits of Cloud Computing for Banking and Finance
Cost Efficiency
Traditional banking IT requires significant capital expenditure (CapEx) on data centres, hardware procurement, and maintenance contracts. Cloud computing converts much of this into predictable operational expenditure (OpEx) on a consumption basis. Banks can redirect capital toward core banking product development rather than infrastructure management — a meaningful competitive advantage in a sector where margins are under constant pressure.
Reliability and High Availability
Financial services require extremely high uptime. In-house IT systems require periodic maintenance windows that can interrupt service. Leading cloud providers design for redundancy across multiple availability zones, enabling near-continuous availability. This is particularly important for payment processing and mobile banking applications, where even brief outages directly damage customer trust and revenue.
Flexibility and Elastic Scaling
Cloud’s pay-as-you-use billing model means financial institutions pay only for the compute and storage they consume. During high-demand periods — such as tax season, quarterly reporting, or major payment events — infrastructure can scale automatically. When demand normalises, resources scale back down, avoiding the waste associated with permanently provisioning for peak load. This elasticity is one of the most operationally significant advantages cloud offers over on-premises infrastructure.
Security and Compliance
Security in financial cloud deployments is nuanced. Private and hybrid cloud models allow banks to keep sensitive data within controlled environments while still benefiting from cloud agility for less sensitive workloads. Public cloud providers implement encryption at rest and in transit, along with permission-based access controls, audit logging, and compliance certifications (such as PCI-DSS, ISO 27001, and SOC 2). That said, banks must conduct their own due diligence on shared-responsibility models — the cloud provider secures the infrastructure, but the institution retains responsibility for application-level security and data governance.
Leading Cloud Applications in BFSI
Application Hosting
Banks host customer-facing web and mobile applications on cloud infrastructure to guarantee high availability and low latency. Cloud hosting eliminates single points of failure and enables content delivery at scale globally — important for institutions with large retail customer bases. Amazon Web Services (AWS), which launched in 2006 and is widely credited with commercialising the modern cloud model, remains one of the dominant platforms for this use case.
Payment Gateways and Funds Transfer
Cloud-based payment infrastructure is already deployed by major lenders for initiating and processing payments and fund transfers. Cloud enables unified customer experience across channels (mobile, web, branch), while the redundancy and uptime characteristics of cloud infrastructure reduce the risk of failed or delayed transactions — a critical concern in regulated payment environments.
ERP and CRM Systems
Enterprise Resource Planning (ERP) and Customer Relationship Management (CRM) platforms delivered as Software-as-a-Service (SaaS) represent one of the most widely adopted cloud use cases across industries. In financial services, SaaS-based CRM tools enable relationship managers to access complete customer profiles and interaction histories from any device, while SaaS ERP platforms streamline back-office financial operations. SaaS reduces the operational burden of software maintenance, patching, and version upgrades — freeing internal IT teams to focus on higher-value integration and customisation work.
Implementation Considerations: Security, Compliance, and Vendor Selection
Cloud adoption in the BFSI sector is not without complexity. Three areas require particular attention:
- Regulatory compliance: Financial institutions operate under sector-specific regulations that govern where data can reside, how it must be protected, and what audit trails must be maintained. Cloud deployment strategies must account for data residency requirements and jurisdiction-specific rules before workloads are migrated.
- Security posture: Adopting cloud does not automatically improve security. Misconfigured storage buckets, overly permissive IAM roles, and inadequate secrets management are common sources of cloud security incidents. A well-defined cloud security framework — covering identity, network, data, and logging — must be in place before sensitive financial workloads move to cloud.
- Vendor selection: Industry practitioners consistently recommend working only with established, well-documented cloud providers who offer financial services compliance certifications and dedicated support. Vendor lock-in risk should also be evaluated, particularly for core banking workloads.
Conclusion
Cloud computing is not merely a supporting technology for Industry 4.0 — it is the infrastructure layer that makes the Fourth Industrial Revolution possible at enterprise scale. For the BFSI sector specifically, cloud adoption delivers measurable advantages in cost structure, operational resilience, scalability, and the ability to deploy AI, analytics, and automation rapidly.
The shift to cloud in banking and finance is no longer a question of if, but of how and how fast. Institutions that approach cloud adoption with a clear strategy — covering security, regulatory compliance, workload selection, and vendor governance — will be best positioned to realise Industry 4.0’s full potential and maintain a competitive edge in an increasingly digital financial services landscape.