Note: The market figures and projections cited in this article are sourced from a third-party market research report (originally attributed to primefeed/Market Expertz, published August 2020). Readers should verify current figures directly with the report publisher before making business decisions.
Overview of the CI Tools Market
Continuous Integration (CI) has become a foundational practice in modern software delivery, enabling development teams to merge code changes frequently, run automated tests, and catch defects early. As DevOps adoption has accelerated across industries, demand for CI tooling has grown correspondingly—driven by the need for faster release cycles, higher software quality, and greater collaboration between development and operations teams.
According to a 2020 market research report, the global CI Tools market was valued at approximately USD 477 million in 2019 and was projected to reach around USD 1,852 million by the end of 2027, representing a compound annual growth rate (CAGR) of roughly 19% over that period. These figures reflect the period before and during early COVID-19 disruption, which the report also assessed for its impact on market dynamics.
COVID-19 Impact on the CI Market
The COVID-19 pandemic accelerated several trends already present in the CI and broader DevOps tooling market. With engineering teams forced into remote work, organisations faced urgent pressure to modernise their software delivery pipelines. Cloud-hosted CI services in particular saw increased interest, as teams needed infrastructure they could access and scale without physical on-premises access. The shift also reinforced the strategic value of automated testing and continuous delivery practices, pushing CI tools higher on IT investment priority lists.
Leading CI Tool Vendors
The market research report identified the following companies as key players operating at both regional and global levels in the CI tools space:
- IBM – Offers CI/CD capabilities through its DevOps and cloud platforms.
- Microsoft – Azure DevOps and GitHub Actions are widely adopted CI solutions.
- Oracle – Provides CI/CD integrations within its cloud infrastructure offerings.
- Red Hat – OpenShift Pipelines (based on Tekton) targets Kubernetes-native CI workflows.
- Puppet – Known primarily for configuration management, with CI/CD pipeline integrations.
- Micro Focus – Offers enterprise-grade ALM and CI tooling.
- AWS – AWS CodePipeline and CodeBuild provide managed CI services on the Amazon cloud.
- CloudBees – Builds enterprise products on top of Jenkins; a major player in commercial CI.
- JetBrains – TeamCity is its flagship CI server, popular in Java and .NET shops.
- Atlassian – Bitbucket Pipelines integrates CI directly into its source control platform.
Beyond these named vendors, the open-source ecosystem—including Jenkins, GitLab CI, CircleCI, and Travis CI—also holds significant market presence, particularly among startups and cloud-native engineering teams.
Market Segmentation by Deployment Type
The CI tools market is commonly segmented by deployment model:
- On-Premises: Self-hosted CI servers installed within an organisation’s own data centre or private infrastructure. This model suits regulated industries with strict data residency or security requirements. Jenkins and TeamCity are frequently deployed this way.
- Cloud (SaaS): Managed CI services delivered as software-as-a-service, where the provider handles infrastructure, scaling, and maintenance. Examples include GitHub Actions, CircleCI Cloud, and AWS CodeBuild. This model reduces operational overhead and is increasingly preferred for its speed of onboarding and elastic scalability.
The trend between 2019 and 2027 has broadly favoured cloud-based deployments, consistent with wider enterprise migration to public cloud infrastructure.
Regional Market Breakdown
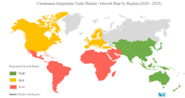
The report analysed CI tool adoption across major global regions:
- North America (USA, Canada, Mexico) – Historically the largest market, driven by high DevOps maturity and concentration of technology companies.
- Latin America (Brazil, Argentina, Chile, Peru, and others) – An emerging market with growing software development sectors, particularly in Brazil.
- Europe (UK, Germany, Spain, Italy, and rest of EU) – Strong adoption driven by digital transformation initiatives and GDPR compliance pressures that have also influenced on-premises versus cloud purchasing decisions.
- Asia-Pacific (China, India, Japan, South Korea, Australia, and others) – A rapidly growing region, with India and China representing significant growth opportunities as engineering talent and cloud infrastructure investment expands.
- Middle East & Africa (Saudi Arabia, UAE, South Africa, and others) – An early-stage but growing market, supported by national digital transformation programmes.
Key Analytical Frameworks Used in the Report
The underlying market research applied several standard analytical frameworks to assess the CI tools landscape:
- Porter’s Five Forces: Evaluates competitive rivalry, threat of new entrants, bargaining power of buyers and suppliers, and the threat of substitutes—useful for understanding how open-source alternatives and cloud hyperscalers affect pricing and competition among commercial CI vendors.
- SWOT Analysis: Assesses Strengths, Weaknesses, Opportunities, and Threats for the market as a whole and for individual players.
- PESTEL Analysis: Examines Political, Economic, Social, Technological, Environmental, and Legal factors influencing market development.
Why the CI Market Continues to Grow
Several structural factors underpin the sustained growth of the CI tools market:
- DevOps and Agile adoption: As more organisations adopt iterative development practices, automated integration pipelines become a prerequisite rather than a nice-to-have.
- Microservices and containerisation: Architectures built on containers and Kubernetes require sophisticated CI pipelines to manage build, test, and deployment across many independent services.
- Security integration (DevSecOps): Teams are embedding security scanning and compliance checks directly into CI pipelines, expanding the scope and value of CI tooling.
- Developer experience focus: Engineering organisations are investing in internal developer platforms where CI pipelines are a central component.
- Open-source ecosystem maturity: The richness of the Jenkins plugin ecosystem, the rapid adoption of GitHub Actions, and the growth of GitLab CI have lowered barriers to entry while simultaneously raising expectations for CI capabilities.
Summary
The CI tools market represents one of the more consistently high-growth segments within the broader DevOps toolchain. With a projected CAGR of approximately 19% through 2027 (per the 2020 report), and with cloud-based deployment models gaining ground over traditional on-premises servers, the competitive landscape is intensifying across established enterprise vendors and cloud-native players alike. Engineering leaders evaluating CI investments should consider not only feature sets but also vendor ecosystem integrations, scalability models, and the total cost of hosted versus self-managed solutions.