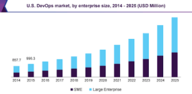
This article summarizes publicly available information about the DevOps Platform market landscape as it stood around 2020–2026. Specific market-size figures and CAGR percentages cited in the original market research report have been omitted because the source document did not disclose them publicly. Readers requiring precise forecasts should consult a paid market research report directly.
What Is the DevOps Platform Market?
The DevOps Platform market encompasses the tools, integrated suites, and cloud services that organizations use to plan, build, test, deliver, monitor, and secure software at scale. Rather than cobbling together dozens of point solutions, enterprises increasingly favour unified platforms that span the full software delivery lifecycle — from source control and CI/CD pipelines through infrastructure automation, container orchestration, and observability.
Demand accelerated sharply in the early 2020s as organizations accelerated digital transformation initiatives and, in many cases, were forced to do so by the disruption caused by the COVID-19 pandemic. Remote-first engineering teams needed reproducible, automated, and auditable delivery pipelines more urgently than ever before.
Market Segmentation
By Platform Maturity / Capability Tier
Market research in this space commonly segments offerings by how deeply DevOps practices are embedded in the platform:
- DevOps Ready — Platforms that provide the foundational tooling (version control, basic pipelines, artifact management) to begin a DevOps journey. Suitable for teams in the early stages of adoption.
- DevOps Enabled — Platforms with deeper automation, policy enforcement, security scanning, and cross-team collaboration features baked in. Suited to teams operating at an intermediate maturity level.
- DevOps Capable — Fully integrated platforms offering end-to-end visibility, AI-assisted insights, compliance automation, and value-stream management. Targeted at enterprise-scale engineering organisations.
By Industry Vertical
DevOps platforms serve a broad range of industries. Key verticals identified in market research include:
- IT & Software — The largest adopter segment; software vendors and managed service providers have the strongest incentive to optimise delivery velocity.
- Banking, Financial Services & Insurance (BFSI) — Regulated environments driving demand for audit trails, change-management controls, and security automation.
- Retail & E-Commerce — High-frequency release cycles for customer-facing applications push adoption of continuous deployment capabilities.
- Telecom — Network function virtualisation and 5G rollout are driving DevOps adoption in carrier environments.
- Education — Growing use of cloud-based learning platforms is pulling educational institutions toward modern delivery practices.
- Others — Healthcare, manufacturing, government, and media all represent growing segments.
By Geography
The global DevOps Platform market spans four primary regions:
- Americas — North America, led by the United States, represents the most mature market. A high density of technology companies, strong cloud adoption, and significant enterprise IT budgets support continued leadership.
- Europe — GDPR compliance requirements and a wave of digital-transformation programmes across financial services and manufacturing drive adoption. Germany, the UK, and the Nordic countries are key contributors.
- Asia-Pacific (APAC) — Rapid growth is driven by digital-native companies in China, India, and Southeast Asia, alongside increasing cloud investment from traditional enterprises.
- Middle East & Africa (MEA) — An emerging region with government-led smart-city and digital economy initiatives beginning to translate into DevOps tooling demand.
Key Market Participants
The competitive landscape in 2020 included a mix of pure-play DevOps tool vendors, open-source project stewards, and large enterprise software incumbents. Notable companies active in this space include:
- Puppet Labs — Infrastructure-as-code automation and compliance enforcement.
- Chef (Progress) — Configuration management and policy-as-code tooling.
- Red Hat (Ansible) — Agentless automation platform widely used for provisioning and orchestration, now integrated with Red Hat OpenShift.
- Atlassian — Collaboration and CI/CD tools including Jira, Confluence, Bitbucket, and Bamboo.
- Docker Inc. — Container runtime and image distribution; central to modern application packaging workflows.
- SaltStack (now part of VMware) — Event-driven automation and remote execution at scale.
- XebiaLabs (now Digital.ai) — Release orchestration and value-stream management for large enterprises.
- VersionOne (now Digital.ai) — Agile planning and project management tooling.
- Broadcom — Enterprise DevOps tooling through the CA Technologies portfolio.
- Spirent Communications — Network and application testing automation.
- DBmaestro — Database DevOps, version control, and release automation.
- VMware — Tanzu portfolio targeting enterprise Kubernetes and application modernisation.
- Cisco — Network infrastructure automation and application performance monitoring.
- IBM — DevSecOps toolchains and hybrid cloud delivery via IBM Cloud and the Red Hat ecosystem.
- Microsoft — Azure DevOps, GitHub Actions, and GitHub Advanced Security form a comprehensive integrated platform.
- CollabNet VersionOne (now Digital.ai) — Enterprise Agile and DevOps lifecycle management.
- Rackspace — Managed DevOps services for organisations that prefer an outsourced operations model.
Since 2020, significant consolidation has occurred. Multiple vendors listed above have been acquired or merged (e.g., XebiaLabs and VersionOne merged into Digital.ai; SaltStack was acquired by VMware). The competitive landscape continues to evolve rapidly.
Key Growth Drivers
- Cloud-native adoption — The shift to microservices, containers, and Kubernetes increases the need for automated build, test, and deployment pipelines.
- Agile transformation at scale — Enterprises expanding agile practices beyond individual teams require platform-level tooling that spans portfolios.
- Security integration (DevSecOps) — Regulatory requirements and high-profile supply-chain breaches are pushing security scanning and policy enforcement left into the pipeline.
- Remote engineering teams — Distributed workforces require cloud-hosted, collaborative toolchains with strong audit and access-control capabilities.
- Competitive pressure on release velocity — Organisations that can release frequently and reliably gain measurable market advantages, creating executive-level demand for DevOps investment.
Challenges and Restraints
- Cultural and organisational resistance — Technology adoption often outpaces the process and cultural changes required for DevOps to deliver its full value.
- Skills shortage — Demand for engineers proficient in CI/CD, infrastructure-as-code, and cloud-native patterns consistently exceeds supply.
- Toolchain complexity and integration costs — Heterogeneous tool estates create integration overhead, security risks, and cognitive load for engineering teams.
- Vendor lock-in concerns — Organisations adopting tightly integrated platforms must weigh portability risks carefully.
- Data sovereignty and compliance — Multi-national organisations face constraints on where pipeline data and artefacts can be stored and processed.
Questions the Market Research Addresses
Buyers of detailed DevOps Platform market research typically seek answers to questions such as:
- What is the projected compound annual growth rate (CAGR) for the global DevOps Platform market through 2026?
- Which industry verticals represent the fastest-growing application segments?
- Which geographic region commands the largest market share, and which is growing fastest?
- How are leading vendors differentiating their pricing models (subscription, consumption-based, perpetual licence)?
- What mergers, acquisitions, and partnership activities are reshaping the competitive landscape?
- How has the COVID-19 pandemic affected short- and medium-term DevOps Platform spending?
- What barriers are slowing adoption in emerging markets, and how are vendors addressing them?
Conclusion
The DevOps Platform market entered the 2020s on a strong growth trajectory, underpinned by cloud adoption, agile scaling, and the urgent need for faster, more secure software delivery. The competitive landscape is consolidating as large incumbents acquire specialist vendors and pure-play platforms mature into comprehensive suites. For engineering leaders and procurement teams, the key strategic questions are not whether to invest in a DevOps platform, but which capability tier fits current organisational maturity, which vertical-specific compliance requirements must be met, and how to avoid toolchain fragmentation as the market continues to evolve.
For precise market sizing, CAGR forecasts, and vendor revenue breakdowns, consult a primary market research report from a recognised analyst firm.